Discharging a Mortgage in WA: How Mortgage Discharge Works When You Sell or Refinance
Most Perth homeowners never see their mortgage on paper. It sits as a line on the certificate of title at Landgate, registered against the property the day you bought it. When you sell or refinance, that line has to come off. That is a mortgage discharge, and in Western Australia it is a formal Landgate transaction that your bank, your settlement agent and PEXA all have a hand in.
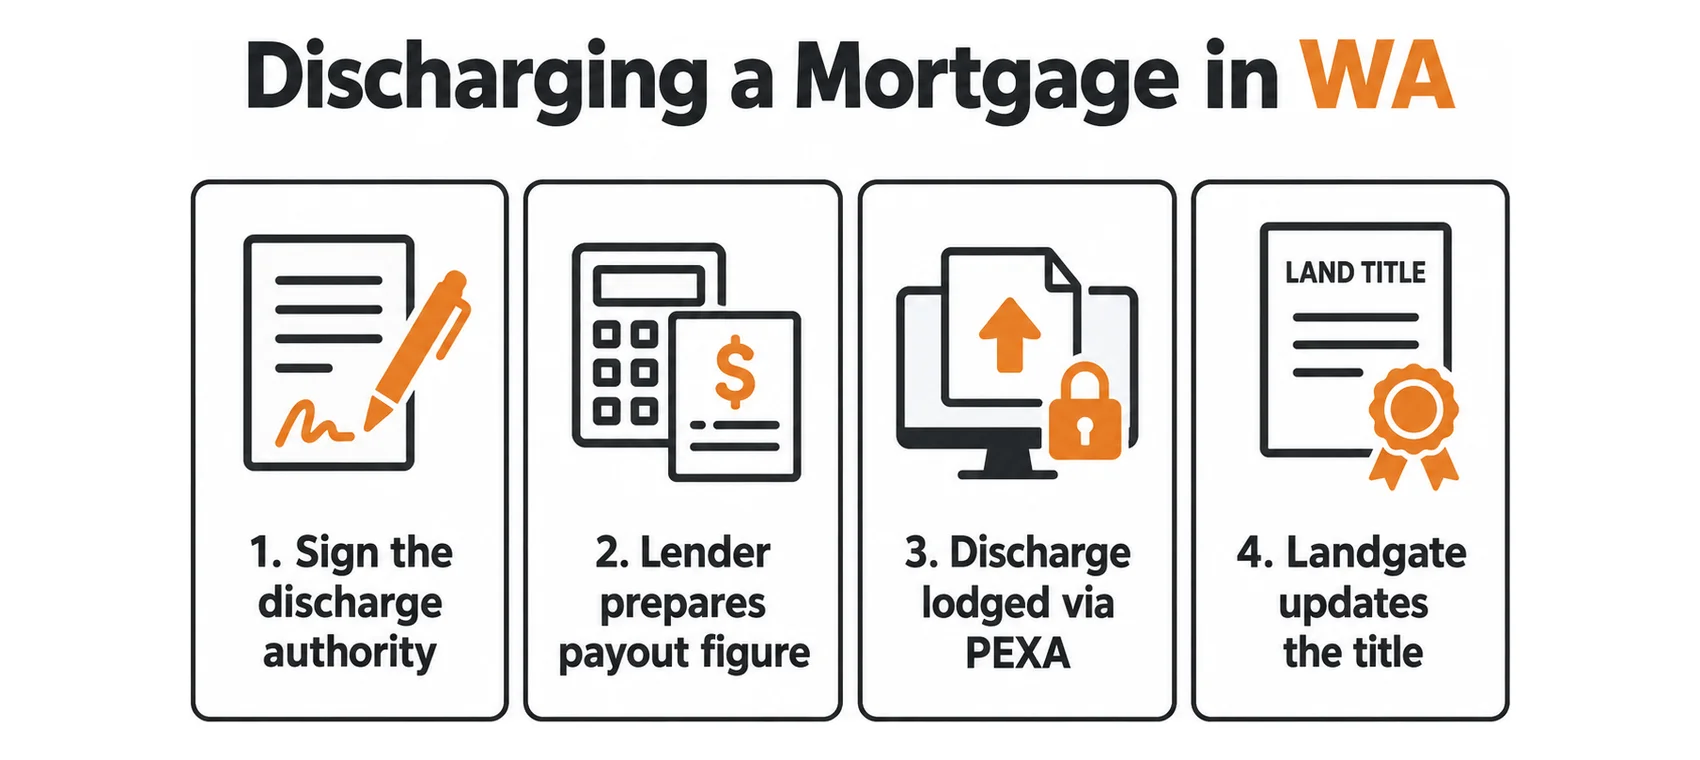
Discharging a mortgage in WA means your lender formally releases its registered interest over your property once the loan is paid out. You start it by signing your lender’s discharge authority form. The lender then prepares a payout figure, the discharge is lodged electronically through PEXA on settlement day, and Landgate removes the mortgage from the title. Lenders commonly take two to three weeks to process the form, so the day you decide to sell or refinance is the day to sign it.
When do you need a mortgage discharge?
Three situations, and the third surprises people.
- Selling with a loan outstanding. The buyer’s lender will not register its mortgage behind yours, so your mortgage is discharged and theirs registered in the same settlement.
- Refinancing to a new lender. No property changes hands, but the old mortgage is discharged and the new one registered on the same day. This is why refinancing in WA still involves a settlement.
- Paying the loan off. If you make the final repayment and do nothing else, the mortgage stays on the title. Some owners discover this years later when they go to sell. You can ask your lender to discharge it at any time.
Step 1: the discharge authority form
Every lender has its own form, sometimes called a discharge authority, discharge request or mortgage release form. It tells the lender you want the loan paid out and the mortgage released, and it authorises the lender to deal with your settlement agent. Every borrower on the loan signs it. If the property is owned by a company or trust, the lender will ask for the relevant authorities as well.
The form usually asks for the property address, the loan account numbers, the reason (sale or refinance), your expected settlement date and your settlement agent’s details. Most lenders now accept it online or by email, and a few still want a wet signature.
Lodge it early. Lenders quote turnaround times of roughly 10 to 15 business days to process a discharge request, and in busy periods it can run longer. A discharge request lodged the week before settlement is one of the most common reasons a Perth settlement is delayed. If you are selling, sign the form the day the contract goes unconditional at the latest. Better still, sign it when you list.
Step 2: the payout figure
Once the lender has your form, it works out exactly what is needed to close the loan on the settlement date: the principal, interest to that day, any fixed-rate break costs, and its own discharge or settlement fee. That is the payout figure. Your settlement agent requests it, checks it against your settlement statement and books the funds.
If the payout figure is higher than the sale proceeds, which can happen after a short hold or on a sale below the purchase price, you must contribute the shortfall before settlement. Your settlement agent will tell you the amount as soon as the figure arrives.
Fixed-rate loans are the ones to watch. Break costs are set by the lender’s contract and can run into thousands of dollars on a large fixed loan when rates have fallen since you fixed. A settlement agent cannot advise you on whether to break or wait. A mortgage broker can, and if you are refinancing, Strategic Mortgages Perth deals with exactly this question.
Step 3: settlement day and PEXA
Nearly all Western Australian settlements now happen in PEXA, the electronic settlement platform. Your lender’s representative joins the PEXA workspace with your settlement agent and, for a sale, the buyer’s agent and the buyer’s lender. At the booked settlement time the funds move in a single sequence: the buyer’s money (or the new lender’s money on a refinance) pays out your loan, the balance goes to you, and the documents lodge with Landgate in the same instant. Our guide to what happens on settlement day in WA walks through the timing.
The discharge of mortgage is one of those documents. Your lender signs it digitally in the workspace, and it lodges together with the transfer of land and the incoming mortgage. If your lender is not ready, nothing lodges. That is why settlement agents chase discharge authorities so hard.
Step 4: Landgate updates the title
Landgate registers the discharge and the mortgage disappears from the certificate of title, usually the same day or the next business day. For a sale, the buyer’s new title shows the buyer as owner and the buyer’s lender as mortgagee. For a refinance, your title shows the new lender in place of the old one. You can order a current title search from Landgate at any time to confirm it.
What does discharging a mortgage cost in WA?
Three separate charges, from three separate parties. Figures below are current at September 2026 and appear itemised on your settlement statement.
| Charge | Set by | Approximate amount |
|---|---|---|
| Landgate lodgement fee, discharge of mortgage | Landgate (from 1 July 2026) | $225.10 per mortgage, no GST |
| PEXA fee, discharge of mortgage | PEXA WA pricing (from 1 July 2026) | $27.39 single title, $55.11 when part of a financial settlement, GST inclusive |
| Lender discharge or settlement fee | Your loan contract | Commonly a few hundred dollars, set in your loan contract |
| Fixed-rate break costs | Your loan contract | Varies with loan size, remaining term and rate movement |
Landgate’s fee is a statutory charge and the same whichever settlement agent you use. It sits on top of the settlement agent’s professional fee, which is covered on our settlement agent fees page. On a refinance you will also pay Landgate’s fee for registering the new mortgage, another $225.10, plus PEXA’s fee for the new mortgage.
Sources: Landgate land transaction fees and PEXA WA pricing, both effective 1 July 2026.
What goes wrong, and how to avoid it
- Late discharge authority. The single biggest cause. Sign it early and keep the lender’s acknowledgement.
- Wrong or missing account numbers. A loan with an offset account or a redraw facility can have several account numbers. Include all of them.
- A borrower who cannot sign. Overseas, in hospital, separated. Tell your settlement agent immediately so alternatives such as a power of attorney can be arranged with your solicitor.
- Payout figure higher than expected. Usually break costs or interest to settlement. Ask for the figure early so a shortfall can be planned for.
- Second mortgage or caveat on the title. Each registered interest needs its own release. A title search at the start of the file picks these up, which is one reason we order one before anything else.
Frequently asked questions
How long does a mortgage discharge take in WA?
Allow two to three weeks from the day your lender receives the signed discharge authority, and longer around Christmas and the end of the financial year. The discharge itself registers with Landgate on settlement day, in the same PEXA transaction as the transfer or the new mortgage.
Who pays the Landgate discharge fee, the buyer or the seller?
The seller. It is the seller’s mortgage being removed, so the $225.10 Landgate fee and the related PEXA fee are deducted on the seller’s side of the settlement statement. The buyer pays the fees for registering their own transfer and mortgage.
Can I discharge my mortgage without a settlement agent?
If you have simply paid off the loan and want the mortgage removed, your lender can arrange the discharge directly, usually for its own fee plus the Landgate charge. For a sale or a refinance in Western Australia the discharge is lodged as part of a PEXA settlement, so a licensed settlement agent or a lawyer manages it.
Does discharging my mortgage close my loan account?
Discharge removes the lender’s interest from the title. The loan account is closed by the lender once the payout is received. Offset or transaction accounts linked to the loan often stay open unless you close them, so check with the lender after settlement.
Selling or refinancing in Perth? Start the discharge now
If you have a settlement coming up, get an instant settlement quote from Strategic Settlements and we will send you the discharge paperwork checklist on day one. Still deciding whether to refinance? Talk to the brokers at Strategic Mortgages Perth first, then contact us when the loan is approved.
The information in this article is general in nature and does not constitute legal, tax, or financial advice. Strategic Settlements is a licensed settlement agent and cannot provide legal or financial advice, including on whether to refinance or break a fixed-rate loan. Fees quoted are current at September 2026 and subject to change. Individual circumstances vary. We recommend consulting a mortgage broker, a solicitor or your lender before making property decisions.